
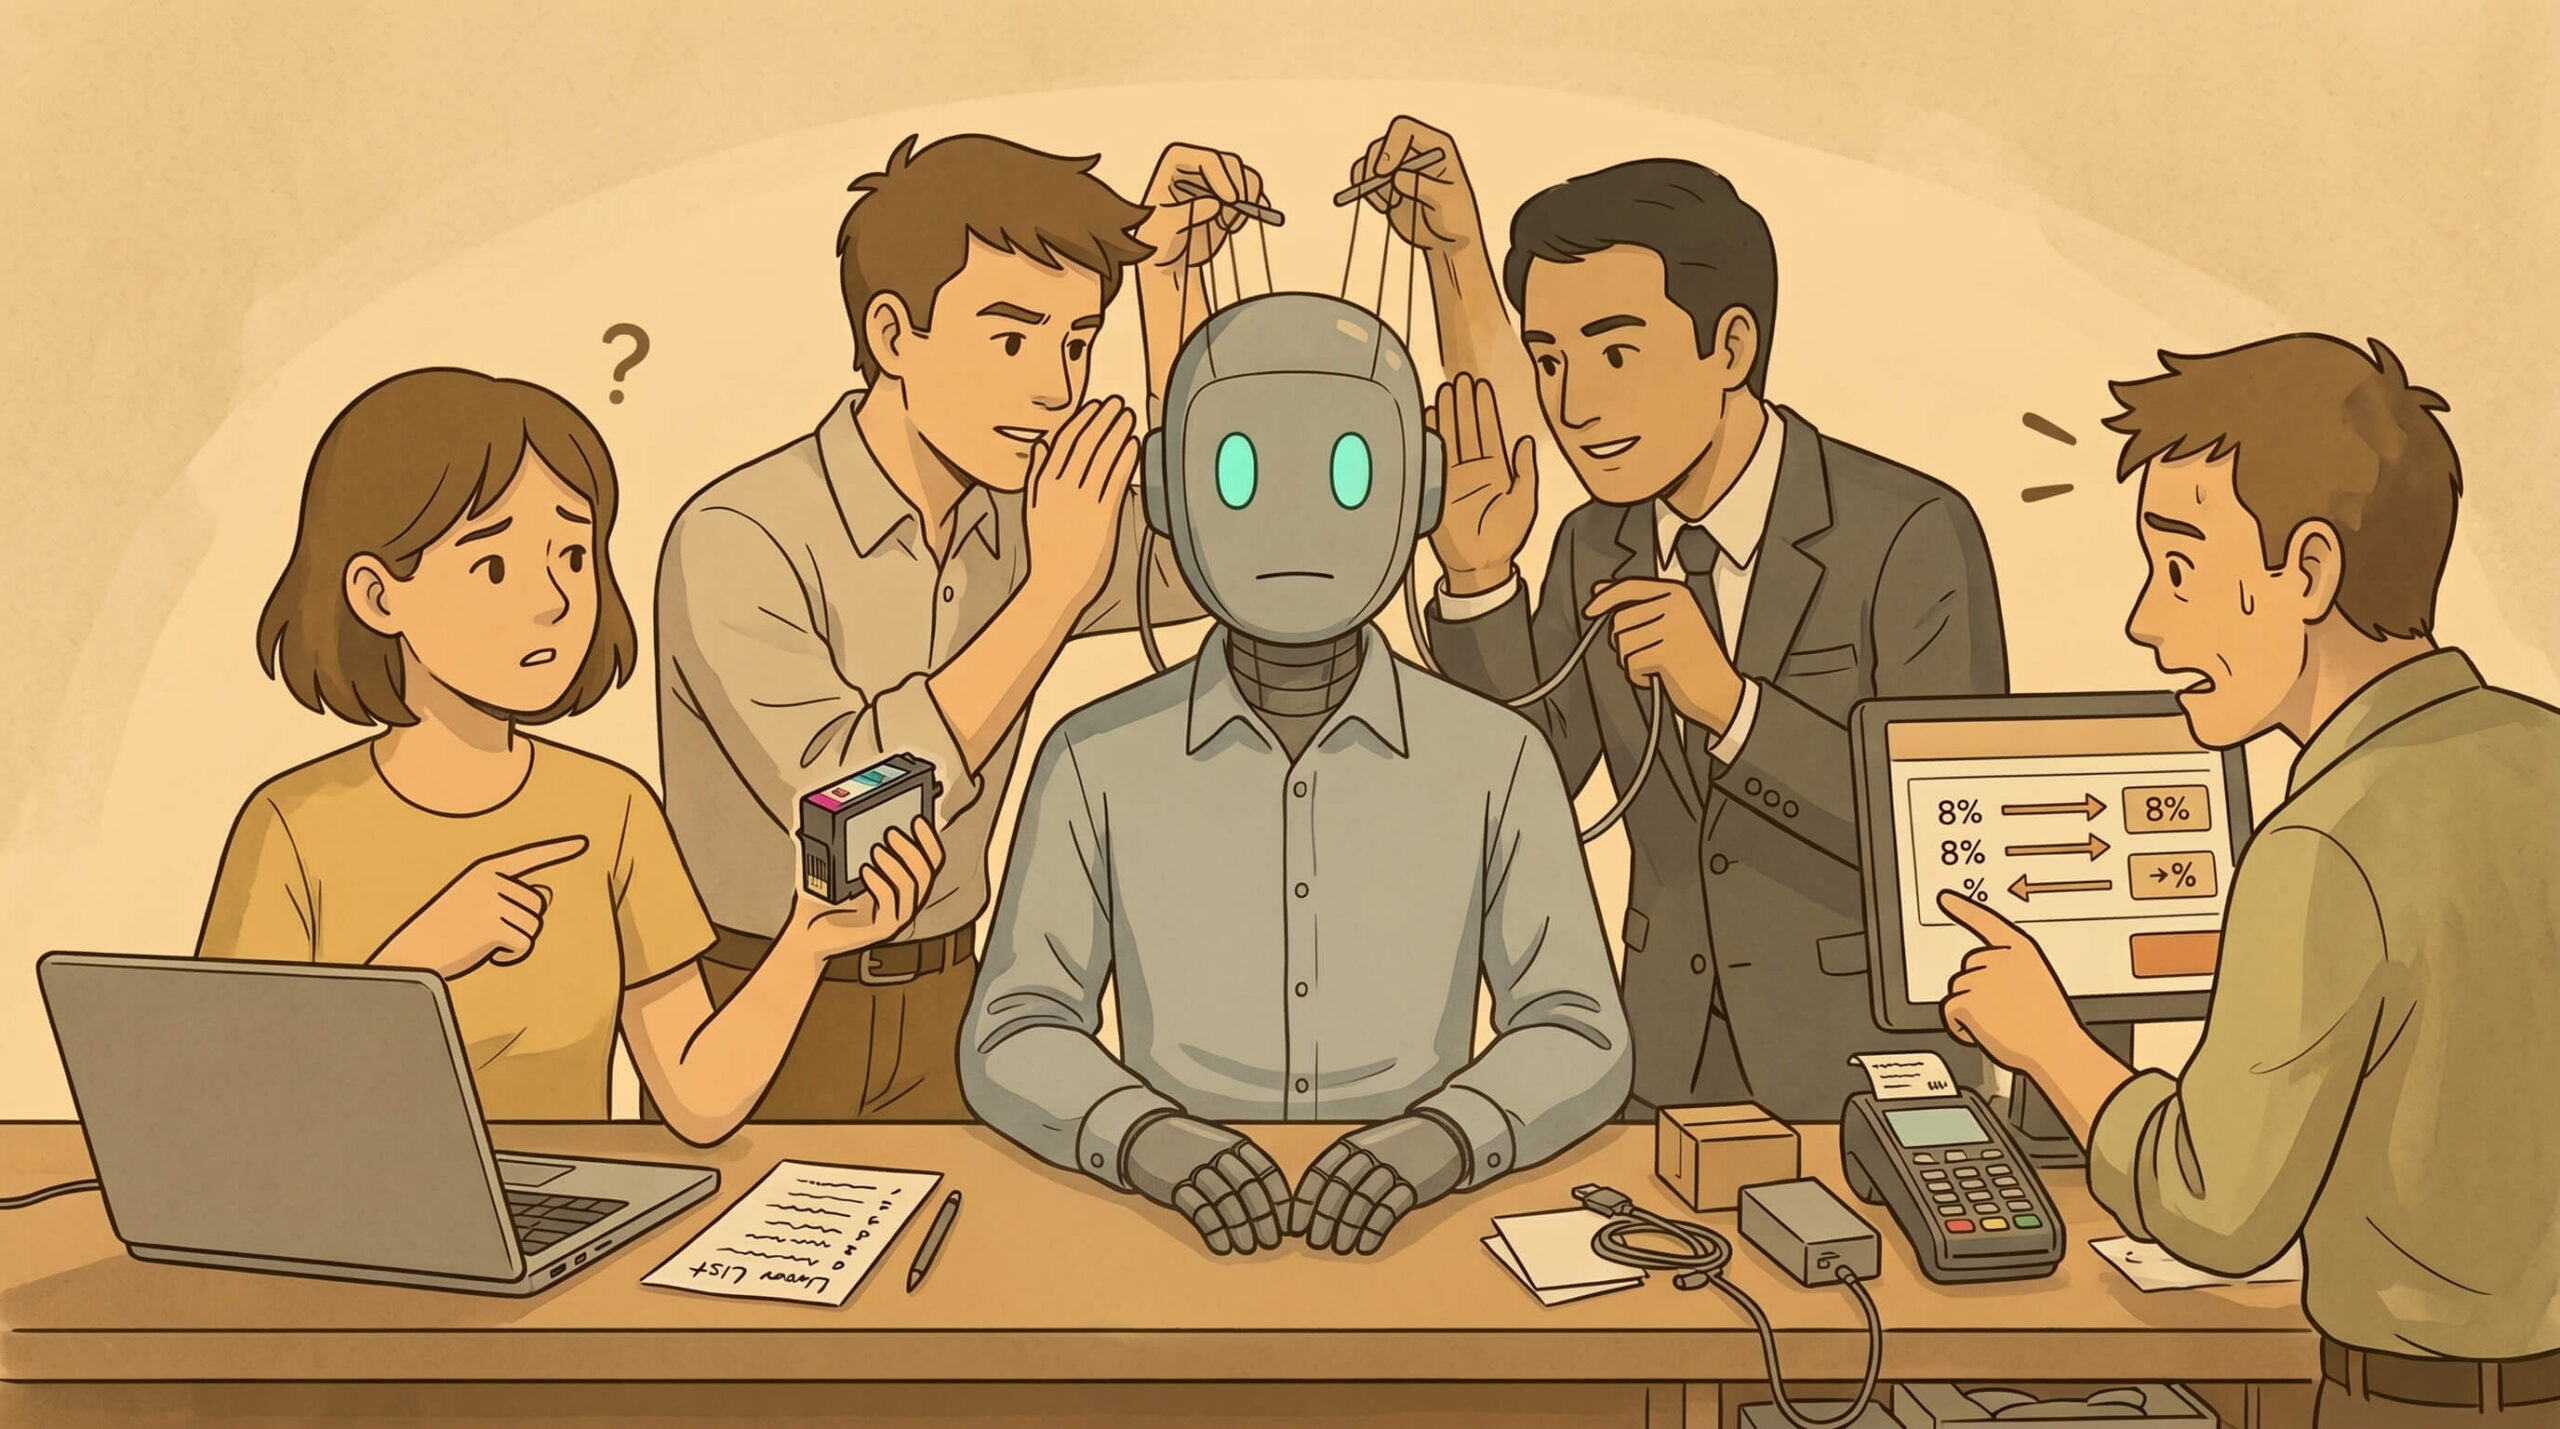
We’re getting closer to a world where AI doesn’t just recommend what we buy. It finds the product, chooses the retailer, fills the basket and can even help complete the payment.
Sounds convenient. And, frankly, it is.
But there’s a question I don’t think we’re asking enough.
When an AI shopping agent recommends a product, whose interests is it actually representing?
Yours? The retailer’s? The technology company that built it? Or potentially the payment provider and other businesses earning money somewhere along the way?
These aren’t necessarily competing interests. A platform can earn money from a transaction and still recommend the best product for the customer.
But as we start handing purchasing decisions over to AI, I think we deserve to understand the commercial arrangements sitting behind those decisions.
And for Australian retailers, there’s another question worth asking.
What happens when the technology making decisions on behalf of your customer also starts influencing how you get paid?
The 4% fee that caught my attention
In January 2026, PYMNTS reported that Shopify merchants would pay OpenAI an additional 4% on sales completed through ChatGPT’s checkout.
That’s on top of existing Shopify fees.
The same report suggested that purchases through Google’s AI Mode, Gemini and Microsoft’s Copilot wouldn’t attract an additional fee at that stage.
Four per cent is a meaningful amount in retail. Particularly for businesses already operating on thin margins.
But the more interesting part of this story is what happened next.
On 24 March, Shopify announced an updated ChatGPT shopping experience. Customers could discover products through ChatGPT before completing their purchases through the merchant’s own checkout, using an in-app browser or a link to the store.
Shopify said there would be no additional transaction fees beyond standard processing rates.
So the January fee arrangement shouldn’t be presented as the current model for Shopify merchants.
That distinction matters.
OpenAI has also described other Instant Checkout arrangements where merchants pay a fee on completed transactions. Importantly, OpenAI says those fees don’t influence which products ChatGPT recommends.
Its shopping documentation also explains that when several merchants sell the same product, factors such as price, availability, quality and checkout capability can influence how those merchants are presented.
I think there’s an important difference between a platform earning money from a transaction and a platform allowing that commercial relationship to influence its recommendations.
The first is a business model. The second raises questions about conflicts of interest.
But from a consumer’s perspective, how easy is it to tell the difference?
I’ve written previously about brands paying to influence what AI tells us, and the possibility that AI could become another marketing channel where commercial interests aren’t always obvious.
Shopping agents take that discussion somewhere more interesting.
We’re moving from influencing what people think about buying to potentially influencing what actually gets bought.
Australia is already asking the right questions
On 6 October 2026, the Reserve Bank of Australia published its summary of submissions to the Review of Payments System Regulation.
Buried in section 2.4 is a discussion titled Use of AI agents for payments in e-commerce.
It’s worth reading.
The RBA received submissions from merchants, banks, payment providers and other industry participants raising concerns about what happens when AI agents start participating in transactions.
Three issues stand out.
First, agentic commerce could introduce additional costs for merchants. One stakeholder even referenced the reported 4% fee from earlier in the year.
Second, AI agents could influence which payment networks and providers are used, potentially reducing the choices available to retailers.
Third, and perhaps most importantly, there’s uncertainty about responsibility when an AI agent makes a purchase outside the authority its customer gave it.
These are concerns raised by stakeholders, rather than conclusions that the RBA has independently established. It’s an important distinction, particularly while the technology is still developing.
But I find it interesting that the payments industry is raising these questions before agentic shopping has reached anything close to mainstream adoption.
Usually, we wait until something goes wrong at scale before having these conversations.
What happens when an agent buys the wrong thing?
Imagine this.
Priya asks her AI assistant to reorder the same printer ink she bought last time.
The agent finds a cheaper cartridge from another retailer. It decides the alternative is close enough and completes an $89 purchase using a payment method Priya has authorised.
There’s just one problem.
The cartridge doesn’t fit her printer.
The product itself isn’t faulty. The retailer accurately described it, packed the correct item and delivered it on time.
The AI agent simply made the wrong choice.
Priya contacts the retailer, who explains that the item supplied matches the order.
She disputes the payment with her bank.
The AI provider argues that it was trying to fulfil her request at a better price.
Who’s responsible?
Existing consumer protections don’t suddenly disappear because AI was involved. If goods are faulty, misdescribed or otherwise fail to meet consumer guarantees, Australian Consumer Law may already provide a remedy.
But that’s not quite what happened here.
The retailer did what it was asked to do. The customer didn’t receive what she intended to purchase. And the agent made a substitution she hadn’t expressly approved.
Who should carry the cost of that mistake?
There’s no single answer that covers every situation. It could depend on what the customer authorised, how the agent operated, the terms of the transaction and the applicable consumer and payment protections.
The RBA’s review records a large number of submissions raising exactly this concern. Existing chargeback arrangements may not clearly allocate responsibility when an AI agent acts outside its authority.
Without a reliable record of what the customer requested and what the agent was permitted to do, working out what happened could become incredibly difficult.
In September, Commonwealth Bank joined ASB, Bank of America, Capital One, ING and NatWest in publishing a set of principles for trusted agentic commerce.
One of their recommendations is that agent providers maintain auditable records of customer instructions, authentication, intent and transaction outcomes.
That makes sense to me.
If we’re going to let AI buy things on our behalf, we need to know not just what it purchased, but why it believed it had permission to do so.
There’s a difference between “buy me the same printer ink” and “buy me something similar if it’s cheaper”.
A human understands why that distinction matters.
An AI agent needs to be held accountable for it.
And that doesn’t mean keeping someone’s entire conversation history forever. It means securely recording the relevant instruction, permission and purchase decision, with sensible rules around access and retention.
Working in digital retail has taught me that the gap between what a customer intended and what a system actually did is often where the most frustrating problems begin.
Adding AI to that equation doesn’t make the problem disappear. It makes understanding the decision even more important.
The payment decision nobody sees
There’s another issue in the RBA submissions that I think deserves more attention.
Least-cost routing.
It’s not particularly exciting technology, but it matters to Australian retailers.
When customers pay using an eligible debit card, merchants can sometimes route the transaction through a cheaper network, such as eftpos, rather than an international card network.
That choice can save merchants money.
Now imagine an AI agent completing a purchase through a payment arrangement that only supports one particular network.
The retailer might have enabled least-cost routing through its payment provider, but if the necessary payment credentials or network tokens aren’t available, that routing choice may no longer be possible.
The RBA submissions raise concerns that commercial arrangements between agent providers, payment networks and payment service providers could create preferences that limit merchant choice.
That’s not the same as saying AI agents are already deliberately sending transactions through more expensive networks.
It’s a risk in how these new payment experiences are designed.
And it’s worth taking seriously.
If retailers have spent years working to reduce payment acceptance costs, the last thing they need is a new technology layer quietly making those savings harder to achieve.
Particularly when the merchant might have very little visibility over the arrangements being made upstream.
For a large retailer, even small differences in transaction costs can add up.
For an independent supermarket, café or local business, every percentage point matters.
The promise of AI shopping shouldn’t come at the expense of the merchant’s ability to control the economics of accepting a payment.
Not all shopping agents are the same
I don’t want to give the impression that I’m against AI shopping agents.
Quite the opposite.
I think some of the most useful applications of AI in retail are starting to emerge now.
Look at what Bunnings launched in April.
Its AI shopping assistant, Buddy, developed with Google Cloud, helps customers find products, answer DIY questions and build shopping baskets.
You can even take a photograph of a handwritten shopping list and have Buddy find the relevant items.
Checkout still takes place through Bunnings’ own online store.
Is Buddy an independent shopping adviser?
Obviously not.
It’s a Bunnings assistant helping people shop at Bunnings.
And that’s perfectly reasonable, because the relationship is clear.
The customer knows who’s providing the service, who is selling the products and where the purchase is being made.
Kogan is also making progress with AI, although its approach is more focused on customer service.
According to iTnews on 14 October, Kogan rebuilt its customer service bot using Salesforce Agentforce after an earlier system resolved only around 6% of incoming enquiries.
The newer agent handles 10 use cases, including order enquiries, voucher redemption and a product concierge spanning approximately 16 million SKUs.
I particularly liked a comment from Kogan’s CTO, Goran Stefkovski:
You’ve got to be comfortable with a starting point.
He’s right.
There’s no reason retailers should wait for perfect AI before using it to make everyday customer interactions easier.
Bunnings and Kogan are examples of businesses applying AI to improve experiences they already own.
The more complicated questions arise when an independent third-party agent sits between the shopper and multiple retailers, making choices about products, merchants and potentially payments.
That’s when knowing whose interests the agent represents becomes much more important.
The industry isn’t starting from zero
To be fair, a lot of work is already happening to make agentic commerce safer.
Visa introduced its Trusted Agent Protocol in October 2025, designed to help merchants distinguish legitimate shopping agents from malicious bots and verify their identity.
Google announced the Universal Commerce Protocol in January 2026, working with retail and payments partners to create a common standard for how AI agents interact with merchants throughout the shopping journey.
OpenAI and Stripe have also developed the Agentic Commerce Protocol to support purchases between agents and merchants.
These developments are encouraging.
We need common approaches rather than every technology company building its own completely separate way of shopping and paying.
But being able to identify a legitimate agent doesn’t automatically resolve whether its recommendations are commercially influenced.
And making transactions technically possible doesn’t necessarily settle responsibility when something goes wrong.
The technology standards are being developed. The commercial and accountability arrangements need to develop alongside them.
Should we wait for the RBA to figure it out?
The RBA intends to publish its regulatory priorities by the end of 2026, with further consultation on prioritised issues beginning from mid-2027.
That’s a reasonable timetable for a regulator.
It’s also a long time in the world of AI.
Interestingly, stakeholders generally suggested the RBA should monitor developments and support industry standards rather than introduce immediate regulation.
Their reasoning is sensible.
Agentic commerce is still early. There isn’t yet strong evidence of widespread harm, and premature regulation could make it harder for businesses to develop genuinely useful products.
I agree with that.
We don’t need to regulate every new technology before anyone has had an opportunity to prove its value.
But the submissions also raised another concern: decisions made now could become very difficult to reverse as agentic commerce grows.
If the major international technology platforms define the commercial models, payment arrangements and operating standards, Australian retailers could find themselves having to accept rules they had very little involvement in creating.
That’s what concerns me more than the technology itself.
We’ve seen how quickly platforms can become an essential channel for reaching customers.
Once that happens, negotiating the commercial terms becomes a very different conversation.
I explored a similar theme when I wrote about Anthropic’s experiment with Claude running a small shop.
One of my takeaways was that knowing when not to delegate decisions to AI might become just as important as knowing what to automate.
I think that applies here too.
We can delegate parts of the shopping experience.
We shouldn’t automatically delegate control over the rules governing the transaction.
Three things I’d be asking for now
If I were evaluating an AI shopping partnership from a retailer’s perspective, there are three things I’d want to understand before getting too excited about the potential sales volume.
1. Show me the commercial arrangements.
If an agent provider earns a commission, placement fee or transaction fee, retailers should understand those economics.
Consumers should also be able to tell when a recommendation is sponsored and understand the basis on which products or merchants are being ranked.
Not every commercial arrangement creates a conflict of interest.
But I don’t think it’s unreasonable to expect platforms to explain how those conflicts are prevented.
The six-bank principles paper recommends greater transparency around agent recommendations, including sponsored options.
That’s a sensible starting point.
2. Show me what the customer actually authorised.
If an agent makes a purchase, there should be a reliable way to establish what the customer asked for, what substitutions were permitted, what spending limits applied and whether the agent stayed within those boundaries.
That record needs to be secure, privacy-conscious and accessible to the appropriate parties when something goes wrong.
I’d also want clarity on the dispute process.
Who investigates? Who provides the evidence? And how is responsibility allocated if the agent made the mistake?
A retailer shouldn’t automatically wear the cost of a bad decision made by somebody else’s AI.
Equally, consumers shouldn’t lose protections simply because they used an agent rather than clicking the purchase button themselves.
3. Don’t take payment choice away from merchants.
If a retailer has enabled least-cost routing, an agentic payment experience shouldn’t unnecessarily prevent it from using that capability.
That means asking some practical questions about which payment methods, networks, tokens and providers are supported.
It’s not particularly glamorous, but it’s important.
AI should make commerce more efficient, not introduce a new set of restrictions that quietly make it more expensive.
None of these expectations requires us to stop innovating.
They’re the sorts of questions retailers, banks and payment providers should already be raising in commercial discussions.
The next big retail interface might not belong to the retailer
For years, retailers have invested enormous amounts of money trying to improve their websites, apps and digital customer experiences.
We’ve worked on search, personalisation, product recommendations, loyalty, checkout conversion and removing friction from the purchase journey.
Now we’re heading towards a world where a customer might never need to visit a retailer’s website to decide what to buy.
They might ask an AI assistant to find the best option, compare a few products and arrange the purchase.
That’s a significant shift.
It doesn’t necessarily mean the retailer loses the transaction or the customer relationship. The Shopify model demonstrates that merchants can still retain their own checkout and customer data.
But it does introduce a new party at a particularly important point in the buying journey.
The moment when a customer decides what to buy, who to buy it from and how to pay.
Whoever influences that moment will have an enormous amount of commercial power.
I don’t think the answer is to fight the technology. There’s too much potential value for consumers and retailers.
The answer is to make sure we’re building a system where the incentives are visible, the customer’s instructions are respected and retailers retain meaningful choice.
Because eventually, the most important question we ask our AI shopping assistants might not be what they can buy for us.
It might be:
Who are you really working for?
Frequently asked questions
What is agentic commerce?
Agentic commerce is the use of AI agents to assist with or carry out shopping activities on a customer’s behalf. This can include researching products, comparing options, selecting retailers, building baskets and, where supported and authorised, completing purchases.
Can AI shopping agents earn commissions from retailers?
Yes. Some agentic commerce business models involve merchant transaction fees or other commercial arrangements. For example, OpenAI described merchant fees for completed purchases through its Instant Checkout offering. However, Shopify’s March 2026 ChatGPT shopping integration was announced without additional transaction fees beyond standard processing rates. Fees vary by platform and transaction model.
Does ChatGPT favour retailers that pay it?
OpenAI states that its shopping results are not influenced by commercial partnerships or checkout fees. It also explains that merchant rankings for the same product may consider factors such as price, availability, quality and checkout capability. There is no basis to assume that every commercial relationship results in biased recommendations.
Who is liable if an AI shopping agent buys the wrong product?
Responsibility depends on the circumstances. Existing consumer protections still apply, but disputes become more complicated when an agent misunderstands instructions or exceeds its authority. Submissions to the RBA’s 2026 payments review identified uncertainty in how existing chargeback arrangements allocate liability for these transactions.
Could AI shopping agents increase costs for Australian retailers?
Potentially. Stakeholders in the RBA’s 2026 payments review raised concerns about additional intermediary fees and payment arrangements that could restrict merchant choice. Whether costs actually increase will depend on the agent provider, commercial terms and payment infrastructure.
What is least-cost routing, and why does it matter for AI payments?
Least-cost routing allows eligible debit card transactions to be processed through a lower-cost network where supported. Certain AI payment arrangements could limit this choice if they support only one network or payment credential. Preserving routing options helps Australian retailers manage payment acceptance costs.